
Intro
We are back with yet another post about CPRT. Below is a selected list of earlier articles we wrote:
Link #1/2 are probably the most important as it discusses the fundamental drivers of the business. But we realized that most of the content is focused on the supply side, not very much has been written about the buyer demand side.
The choice to focus on supply is not misguided since CPRT is indeed very dependent on auto insurers sending totaled vehicles.
Although CPRT also acts as a principal by buying totaled cars outright and selling them, this segment is not high ROIC since they have to carry the inventory on their balance sheet.
In contrast, the consignment model has far better returns, where CPRT acts as an agent for insurers who sends those damaged cars.
About 80% of units that come to CPRT are from insurers. The remaining 20% comes from non-insurance:
Blue Car. This segment supplies damaged cars from banks, rental car companies, and fleets. Rental car suppliers are particularly interesting, because every day that a rental car is off the road translates to revenue lost. So a rental company is time sensitive when thinking about whether to repair or auction a damaged car. The more time passes, the more likely they will auction it. Furthermore, rental cars are unlikely to fetch a good rate if they are even slightly damaged.
Rental companies also have shorter turnover time than an insurer. As this segment continues to become larger, it can show up in metrics like “cycle time” which fell -9% in Q1 2026.Dealers. Copart Dealer Services (CDS) and NAPA (National Powersports Auctions) for dealers that repossessed vehicles for whatever reason.
Copart Direct. This is the principal model mentioned above.
Therefore, it’s obvious why we spend much time describing the economics of CPRT’s supply side.
For a more complete understanding, let’s explore the buyer demand side as there are also very interesting details that we should appreciate.
Types of Buyers
The demography of buyers are fragmented since the top 10 biggest buyers make up only a low single-digit percentage of all vehicles CPRT sell in the US. Buyers can be licensed vehicles dismantlers, rebuilders, repair licensees, used vehicle dealers, and exporters.
The general public is actually only a small fraction of participation. To buy salvaged vehicles in the US, the individual has to go through a registered broker. These brokers hold licenses that allow individuals to bid under their credentials. The process is costly because these brokers charge their own fees too.
Therefore, the auction game is played by companies rather than individuals.
CPRT sells membership tiers for access to their auction platform. There’s 3 tiers: Guest, Basic, Premier. There are some countries like the UK where they only offer Guest and Basic tiers, suggesting that the market is still not matured.
The difference between tiers mainly is their fee structures and quality of access.
Guest is free of charge. You can browse and receive updates, but cannot bid.
Basic cost $99/year. You can bid on one vehicle at a time with limited buying power that requires a deposit. You also get free yard previews during designated business hours.
Premier cost $249/year. You have bid limit of up to $100k per day, can bid on multiple vehicles and have priority customer support.
One of the more important buyer groups are exporters. These are companies that buy cheap salvaged cars from the US and sell them for more in other countries. They are important because they indirectly bring buyers from all over the world, contributing to the liquidity that CPRT’s two-sided auction platform requires to function well.
Exporters exist because the price of a new car is expensive relative to purchasing power in countries like Latin America, Africa, or Eastern Europe. Driving a damaged vehicle makes economic sense for some people living there. Not only is it cheaper, but they also have slacker legal requirements.
For example, cars with faulty airbags cannot be legally driven in the US, but they are fine in Mexico. Or the car has a damaged electronic dashboard, that’s no problem for someone in Bulgaria.
In volume terms, 39% of vehicles sold in US auctions go to an international buyer. In price terms, that number is ~50%!
This is a symbiotic relationship; CPRT and exporters benefit from each other’s existence with each party extracting surplus from the value chain.
So CPRT buyer base is really very diversified. Even though the income statement says that 85% of revenues are from US region, but the underlying demand is actually coming from overseas.
Because the pool of international buyers is so large, they collectively bid up prices, driving up the average selling price (ASP). This implies that US insurers who supply the cars get a higher return — they could not have achieved this without the existence of CPRT, and so the relationship is very dear.
Buyer Fees
You can find the details on fees structure here.
There are 2 main variables that affect the final fee:
Non-clean or Clean title.
(a) Non-clean title is another term for “salvage vehicle”, meaning that it was declared a total-loss by an insurer at some point (even if it’s repaired and roadworthy). CPRT obtains the title on the insurer’s behalf — this is a complicated process as the rules differ by state, but is also a value-added service that CPRT offers.
(b) Clean title means the vehicle has never been declared a total-loss.Standard or Preferred pricing. To qualify for Preferred, a buyer must have bought 25 vehicles of at least $75,000 over 12 months, across at most 5 accounts (this criteria covers roughly all of its professional clients). Those who don’t meet these criteria fall under Standard.
The rest are fixed: gate fees $95, and environmental fees $15.
Put together, for pro clients their fee schedule vs. bid price looks like this (assume secured payment, exclude title shipping and auxiliary charges):
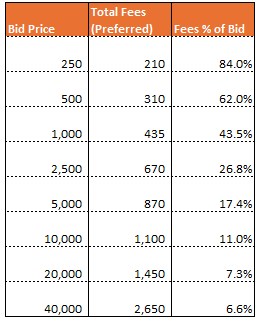
The fee schedule is regressive in nature, thus we get convexity in the fee revenue curve:
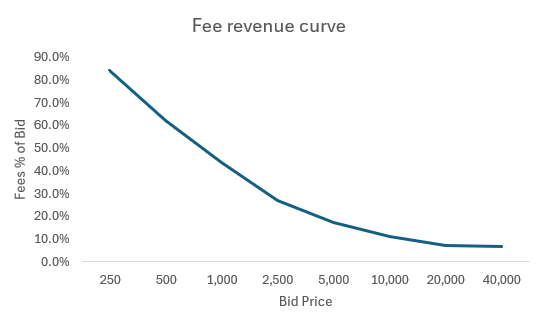
As a result, the gradient at each bid price is different. This has some nuanced implications on unit economics. We cannot assume a linear relationship between ASP movement and fee revenues.
An extreme example would be if CPRT sells a hundred $250 wrecks, it collects $21k in fees. But if CPRT sell a price equivalent $25,000 wreck, it only collects $2,125. We should keep in mind that higher number of low-value wrecks require more towing and yard space which doesn’t immediately mean high operating profits.
In other words, CPRT unit economics is driven more by mix than average prices.
Since most of the car bids are above $15k where fees % are capped, if used car prices rise, all else equal, CPRT will earn less incremental revenues per unit relative to ASP (absolute dollars will of course increase).
This was what happened in the recent quarters where revenues per unit increased less than ASP. The instinctive reaction would be to say CPRT has lost pricing power to competitor IAA.
Pause for a moment… what happens if ASP fell instead?
Yes, their revenues per unit will decrease less than ASP:
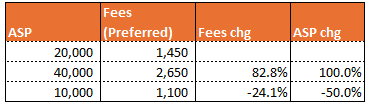
On the surface it can look like CPRT is structurally designed to be less sensitive to changes in ASP — this is only true if number of units sold increased.
Falling ASP will trigger insurers to deem more vehicles as total-loss. A lower sensitivity to falling ASP is an illusion of resilience if CPRT cannot sell more units in such a scenario.
We know this is complicated. Analysts have been asking questions about mix and pricing for the longest time ever, and management always point to the number of units sold as the primary driver of growth.
To hit on this topic further, we know that PGR stopped sending units to CPRT, but that might not be a bad thing.
Despite PGR being the largest auto insurer, we suspect CPRT is less interested in PGR's salvage because of the lower ASP it insures compared to its competitors. In fact, CPRT intentionally rejected price negotiations with PGR.
This low-ASP high-volume strategy doesn’t fit with CPRT, whose strategy for the past few years has been focused on high value salvage to lower earnings volatility, since the high end of the fee curve is flatter. Note: This is guesswork from the loss of PGR coinciding with ASP at all-time high.
At this point you should start to notice the information asymmetry that exist between buyers and suppliers.
Insurers (suppliers) have to negotiate long-term contracts with CPRT and these terms are trade secrets. Insurers cannot go directly to buyers because it is not their core business model and they don’t have the infrastructure to do so.
Buyers have no negotiation power with CPRT, they are price-takers.
CPRT sits between them with information advantages about both parties, hence exploiting this asymmetry through pricing power. However, CPRT is also constrained because insurers are the lifeblood of the business, there are only a few large auto insurers so keeping them happy is a priority.
Competitor IAA
We know CPRT and IAA operate in a duopoly, but are they competing on price? What is IAA fee schedule?
No surprises, both exercise rational pricing otherwise the duopoly wouldn’t have lasted. IAA fees are almost the same, they actually have slightly higher fixed service fees.
If they are not fighting over prices, then where is the battleground?
Service quality — especially on the supply side.
Insurers want to get rid of salvage cars fast (at a good price) to recoup some of the claims losses. So, there are 2 important battlegrounds:
Fast turnover + high bid prices. This means efficient towing, title handling, deep auction liquidity.
Response to catastrophic disasters (hurricanes). Obviously, these events contribute a lot of salvage units. Whoever can response effectively wins the battle.
Theoretically, insurers are not stuck with IAA or CPRT, but in practice switching carries logistical cost. The value proposition for winning is to provide insurers the best salvage price and service.
Cyclical Problems
For the ending notes, we think it's worthwhile to remind ourselves of the recent problems that CPRT is facing. Afterall, the stock wasn't cut in half without reasons.
We start from 2023 when auto insurers realized that inflation was causing inadequate reserves. So they adjusted prices upwards for a huge +20%.
Underwriting margins were restored in 2024, but consumers felt the pinch and started to drop renewals and deductibles. The entire salvage pool shrunk.
In 2025, PGR gained market share from State Farm and became the largest insurer. At the same time, they used this as leverage to negotiate for better terms which CPRT refused. So PGR shifted most of their salvage to IAA.
Unit volumes fell for a few straight quarters, and the market feared that IAA is going to beat CPRT.
These are cyclical issues.
Clearly, insurers hiked prices too much (typical over/undershoot estimation) causing the salvage vehicle pool to shrink across the board, and CPRT was disproportionally affected because it disagreed with lower supplier fees with PGR.
Currently, PGR is no longer growing inforce policies as quickly. In fact, it has slowed down significantly:
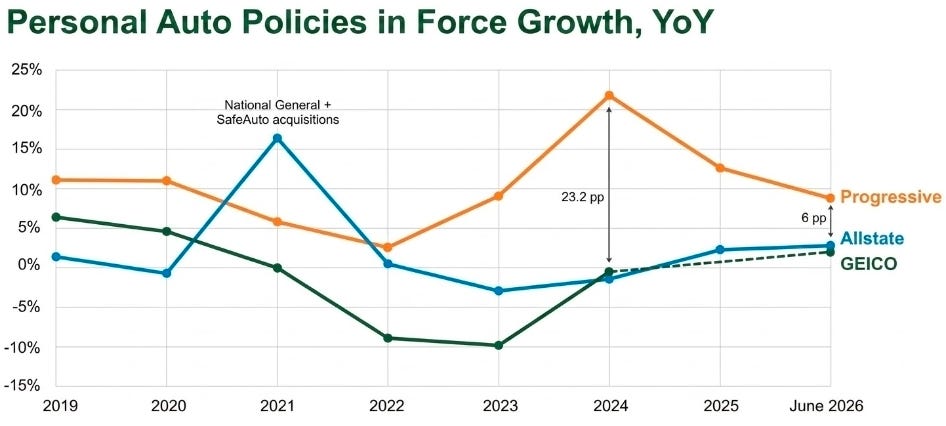
PGR must slow down because it's impossible to grow fast and yet be profitable in a commodity-like auto insurance industry.
We think that the market has once again exaggerated the issues. We should watch if the cycle to turns soon and whether CPRT unit volumes increase.